What is the scope and industry significance of the Rapid Strength Concrete Market?
Our analysis indicates that the Rapid Strength Concrete Market represents a critical sector in modern infrastructure, valued at $341.34 Billion in 2026. This market encompasses specialized cementitious formulations engineered for ultra-fast setting times and high early compressive strength, enabling rapid turnaround on critical transportation and industrial projects governed by strict Department of Transportation (DOT) and ASTM standards.
Structural Growth Drivers, Restraints, Challenges, and Opportunities in Rapid Strength Concrete Market
The Rapid Strength Concrete Market industry trends are heavily propelled by urbanization and the urgent need to minimize traffic disruption during highway repairs. However, high material costs and strict curing temperature constraints act as significant restraints. Opportunities abound in smart infrastructure projects requiring quick-setting formulations from innovators like CTS Cement Manufacturing Corp. and Sika AG.
The Shift Toward Ultra-Fast Setting Formulations
Emerging growth patterns within the Rapid Strength Concrete Market highlight a definitive shift toward high-performance and eco-friendly binders. Contractors increasingly demand self-compacting and fiber-reinforced variations to reduce labor overhead. Market leaders such as BASF SE and CEMEX S.A.B. de C.V. are aggressively investing in proprietary chemical admixtures to enhance early-age strength gain without sacrificing long-term durability.
COVID-19 Impact Analysis on Rapid Strength Concrete Market
The pandemic severely disrupted supply chains for key raw materials like Portland cement and specialized pozzolans, initially stalling the Rapid Strength Concrete Market recovery trajectory. However, government stimulus packages targeting shovel-ready bridge and airport rehabilitation projects rapidly accelerated post-pandemic demand, allowing major suppliers to recover ground and exceed pre-crisis production volumes by 2026.
Competitive Benchmarking and Strategic Dynamics
Competitive intensity in the Rapid Strength Concrete Market is high, characterized by aggressive M&A activity and regional footprint expansion. Established giants like Holcim Ltd. and LafargeHolcim Ltd. leverage extensive distribution networks, whereas specialty players like Mapei Corporation and Euclid Chemical Company compete through advanced chemical formulations and dedicated technical support services.
Executive Summary of the Rapid Strength Concrete Market
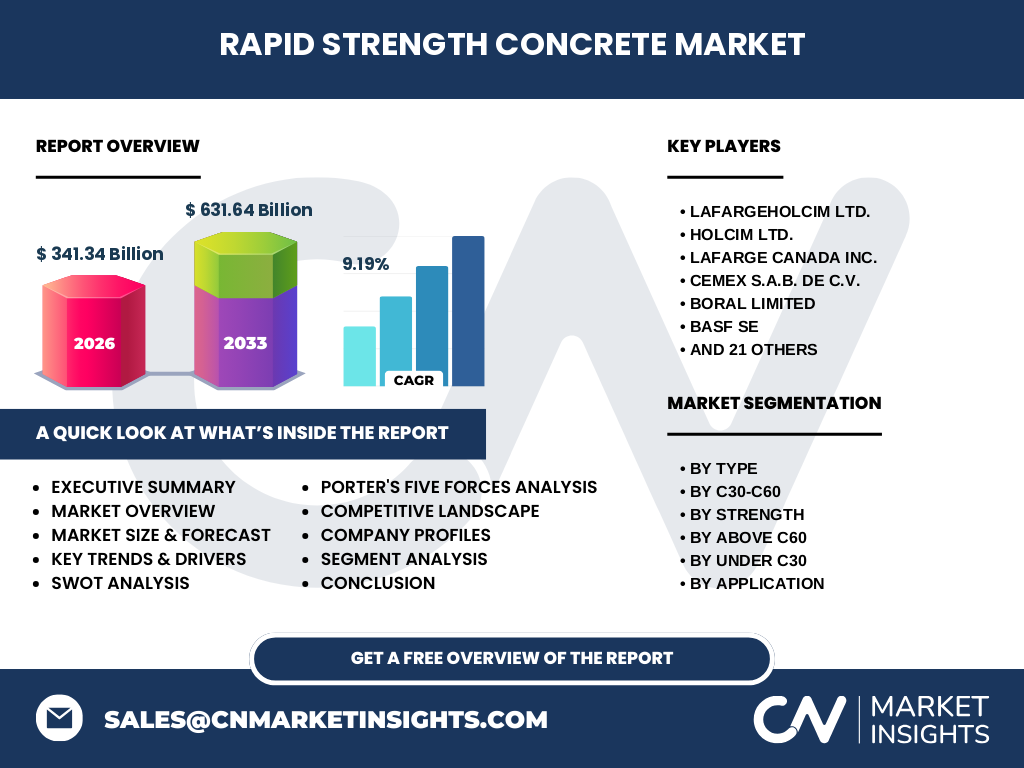
Our comprehensive Rapid Strength Concrete Market analysis reveals a thriving sector poised to expand from $341.34 Billion in 2026 to $631.64 Billion by 2033 at a robust CAGR of 9.19%. This exceptional growth is driven by surging global investments in resilient transportation networks, airports, and urban rail systems that demand minimal downtime.
Long-Term Market Forecast from 2027 to 2033
The data suggests the Rapid Strength Concrete Market market size will nearly double, surging from $341.34 Billion to reach $631.64 Billion by 2033 at a 9.19% CAGR. This trajectory reflects sustained governmental capital expenditures toward smart cities and urgent structural retrofits, favoring suppliers capable of scaling low-carbon, fast-curing production.
Segmentation Analysis of the Rapid Strength Concrete Market
The market is segmented by type (Under C30, C30-C60, Above C60), strength (0-40 MPa, 40-80 MPa, Above 80 MPa), and application (Airport, Building Floor, Dockyard, Formed Work, Rail Network, Road or Bridge, and Other Applications). C30-C60 sub-segments like Self-Compacting and High-Performance Concrete dominate commercial applications, while Above C60 UHPC captures high-stress bridge and dockyard contracts.
Regional Market Analysis and Geographic Distribution
Geographic performance within the Rapid Strength Concrete Market varies based on regional infrastructure maturity and regulatory mandates. North America and Europe prioritize rapid highway and bridge rehabilitation using proprietary blends from TITAN America LLC and Hanson UK Ltd., whereas Asia-Pacific drives volume consumption through massive rail and airport expansion initiatives.
In-Depth Regional Review of High-Growth Zones
Asia-Pacific leads consumption volume due to aggressive state-backed mega-projects in transportation. Meanwhile, North America demonstrates strong demand for proprietary rapid-setting repair mortar systems governed by strict Federal Highway Administration (FHWA) guidelines. European markets focus heavily on low-carbon rapid-strength binders to comply with stringent European Union environmental directives.
Company Profiles and Strategic Positioning
Industry leaders like Lafarge Canada Inc., Boral Limited, and Aditya Birla Group Pvt. Ltd. secure competitive advantages via localized manufacturing hubs and vertically integrated raw material supply chains. Specialty compounders like Instarmac Group plc and Quikrete Companies focus on packaged, pre-blended dry mixes tailored for rapid retail and municipal patch repairs.
Porter's Five Forces Analysis of the Industry
In the Rapid Strength Concrete Market, supplier power remains moderate due to abundant industrial mineral availability, but threat of new entrants is constrained by high R&D costs for chemical admixtures. Buyer power is counterbalanced by the critical need for certified performance standards, while substitute materials face adoption hurdles in high-stress infrastructure applications.
SWOT Analysis for Rapid Strength Concrete Market Stakeholders
Key strengths include ultra-fast setting times and exceptional early compressive strength, though weaknesses involve higher material expense compared to standard concrete. Opportunities lie in smart infrastructure retrofits, while threats stem from raw material price volatility and strict carbon-reduction mandates impacting traditional cement production.
Value Chain Analysis from Raw Materials to End-Users
The value chain spans raw material extraction (aggregates, specialized cements, chemical admixtures), formulation by leaders like Fosroc Inc. and Arkema SA, distribution via ready-mix suppliers, and final placement by specialized contractors on airports, dockyards, and road networks. Each tier demands rigorous quality control to ensure target setting times are met.
Investment Insights and High-Potential Growth Areas
Our research indicates that investors should target companies developing low-carbon, ultra-high-performance concrete (UHPC) formulations. Firms partnering with regional transit authorities and port operators—such as Conmix Ltd. and Aggregate Industries UK Ltd.—are best positioned to capture high-margin municipal contracts and outperform broader market growth.
Conclusion and Key Takeaways for Industry Stakeholders
Reaching $631.64 Billion by 2033, the Rapid Strength Concrete Market offers compelling opportunities for stakeholders investing in advanced material science and sustainable chemistry. Success relies on balancing rapid strength performance with emerging environmental regulations across critical transport infrastructure applications.
Research Methodology and Baseline Estimation
Our baseline estimates for the Rapid Strength Concrete Market are triangulated by combining macroeconomic industrial production indices, trade registry data, and primary stakeholder interviews with executives from Buzzi Unicem S.p.A., CEMEX, and regional civil engineering authorities to ensure precise market sizing.
Scope of the Report and Coverage Parameters
This report covers global developments, regional performance variations, and detailed product segmentation within the Rapid Strength Concrete Market from 2026 to 2033. Exclusions include standard low-strength residential concrete applications that do not utilize rapid-setting chemical accelerants or specialized cementitious formulations.
Recent Developments and Strategic Industry Moves
Recent market dynamism includes strategic acquisitions, green cement product launches, and collaborative R&D partnerships between chemical giants and ready-mix producers. Innovators like ACC Limited and Westbuild Products Pty Ltd. have recently introduced eco-friendly, fast-curing dry mortar lines designed to reduce carbon footprints while meeting rigorous highway engineering specifications.